Ningbo Home Seller Trapped in 'Pig-Butchering' Scam: The Dark Truth Behind House Purchase with 200,000 Yuan Premium
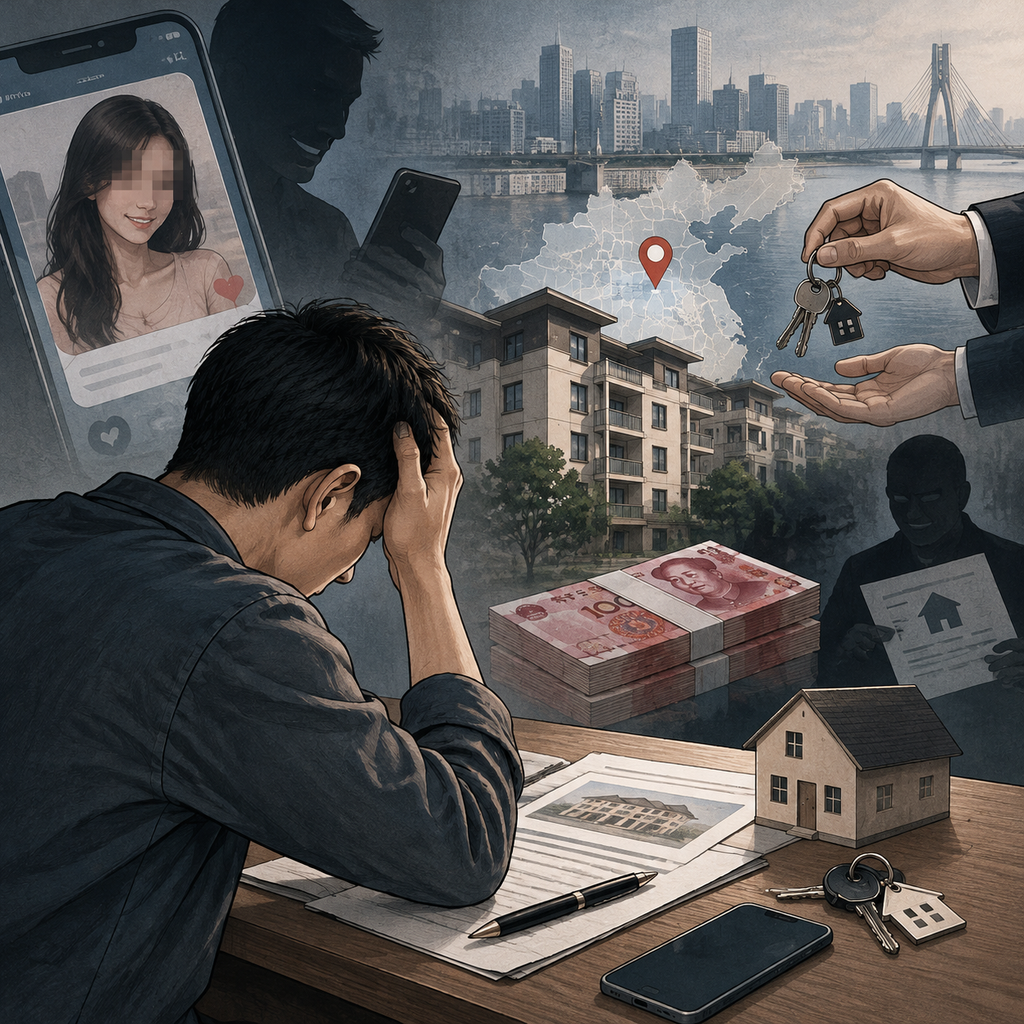
In late 2024, Ms. Zhang from Ningbo, Zhejiang Province, experienced the worst real estate transaction of her life. She planned to sell a 180-square-meter second-hand house but fell into an elaborate scam set up by a so-called "high-paying buyer." The buyer promised to pay 200,000 yuan above the market price for a full-cash purchase. In reality, he only paid 480,000 yuan (including a 10,000 yuan deposit and 470,000 yuan down payment) before obtaining the property certificate, then mortgaged the house for 1.8 million yuan. To this day, Ms. Zhang's house remains under mortgage, facing a nightmare of massive financial loss.
The Trap of "High-Pricing Buyer"
After listing her property in Yinzhou District, Ningbo, a self-proclaimed intermediary named "Xiao Ying" approached Ms. Zhang, claiming a client named Duan was willing to pay 3.15 million yuan for her house—about 200,000 yuan above market price. Duan showed strong purchase interest, repeatedly emphasizing "urgency" and demanding a quick contract signing. Ms. Zhang was tempted, thinking she had found a straightforward buyer.
On December 12, both parties signed the first purchase contract, agreeing on a total price of 3.15 million yuan, to be paid in full at once, with property transfer upon payment. This contract was subsequently filed with the housing authority. However, Ms. Zhang later recalled that when signing, the contract had no electronic seal, and she had no idea it would become a legally effective registered contract.
The Double Contract Deception
Three days after signing the first contract, the intermediary presented another contract. This time the payment terms changed: a 10,000 yuan deposit, 470,000 yuan down payment, and the remaining 2.67 million yuan through commercial mortgage. The intermediary explained that the first contract was merely a "draft" to help the buyer get bank approval, and Ms. Zhang only needed to cooperate by signing another one.
Believing this explanation, Ms. Zhang signed the second contract. On December 24, she received the 470,000 yuan down payment and some cash, totaling 480,000 yuan. The next day, the house was smoothly transferred to buyer Duan's name. However, the mortgage payment never arrived.
When Ms. Zhang checked at the government service center, she discovered that the first full-payment contract was the one actually registered and effective, while the second mortgage contract was invalid. This meant Duan only needed to pay a small down payment to legally obtain the property certificate.
Mortgage Fraud: A Premeditated Scheme
What made Ms. Zhang even more devastated was that, the day after the property transfer, buyer Duan had already mortgaged the house to others, obtaining 1.8 million yuan in mortgage loans. Of this 1.8 million, Duan gave intermediary Shi 500,000 yuan, used the rest to pay personal debts, and transferred some to his ex-wife.
Police investigation revealed that Duan had divorced before the incident and left with nothing, suggesting the entire purchase was likely premeditated. The so-called intermediary "Xiao Ying" wasn't his real name either; his surname was Shi, and he had previously been involved in other real estate disputes—a veteran at using property transactions to commit fraud.
Currently, Duan and Shi have been criminally detained by police. However, for Ms. Zhang, her house remains under mortgage, facing a "loss of both money and property"—the house has been transferred to the buyer, but she received less than 500,000 yuan, while the buyer had already mortgaged and cashed out the property.
The Transaction Loophole: The Cost of Skipping Supervision
This case succeeded simply because both parties skipped the capital supervision process. In traditional second-hand housing transactions, there's a time gap between property transfer and payment, and scammers exploited this gap.
The standard capital supervision process works like Taobao shopping: the buyer deposits the purchase funds into a special supervision account designated by the housing authority, controlled by a third-party supervisor; after completing the property transfer procedures and the buyer obtains the new property certificate, the supervision account automatically transfers the funds to the seller. Throughout this process, property transfer and payment are synchronized, and funds don't flow through any personal or intermediary accounts.
But in Ms. Zhang's case, the buyer paid only about 500,000 yuan in down payment to control a property worth over 3 million yuan. After obtaining the property certificate, Duan immediately mortgaged and cashed out the property, completing the entire process within 48 hours.
This case is not isolated. In 2026, multiple regions nationwide will implement free capital supervision policies to fundamentally prevent such transaction loopholes. Second-hand housing transactions will then be protected like "Alipay," ensuring "clean transactions of both money and property." But before the new policies fully take effect, buyers and sellers must remain vigilant.
Prevention points: Any transaction request skipping the capital supervision account could be a scam; verify the other party's identity and credit status before signing contracts; remain highly cautious about "good deals" significantly above market price; don't blindly believe intermediaries' one-sided statements—all agreements must be in writing and verified; immediately check property registration information after transfer to confirm any encumbrances like mortgages.
If you encounter similar fraud, immediately preserve chat records, transfer receipts, contracts, and other evidence; report to police promptly; and contact property registration authorities to take necessary preservation measures.

本站爆料正文为用户真实投稿(UGC),AI 仅用于跨语言翻译与辅助整理,全部内容均经人工审核核实后发布,仅供公众防骗参考。